
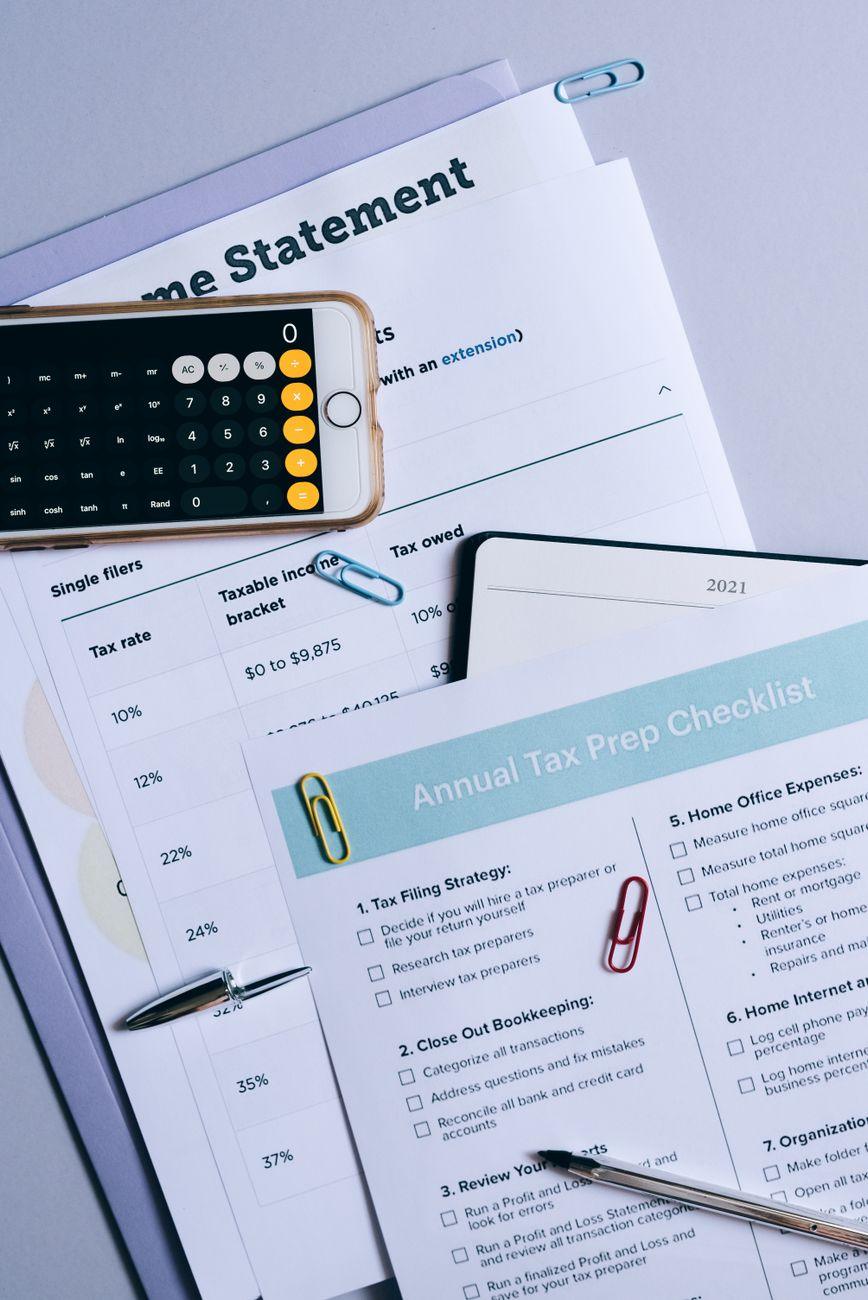
The Progressive Puzzle: Unpacking How Tax Brackets Work
I remember staring at my first tax return, totally bewildered. You hear about tax brackets all the time, and people grumble about them, but nobody really spells out how they actually work to figure out your tax bill. It’s not like your entire income gets slapped with the highest rate you fall into. That would be brutal, right? Instead, Uncle Sam uses a progressive tax system, which sounds fancy but just means different portions of your income are taxed at different rates.
So, imagine you earned, say, $60,000 last year. The IRS divides that income up. The first chunk, let’s say the first $10,000, might be taxed at a low rate, like 10%. That’s your 10% tax bracket. Then, the next portion of your income, maybe the amount between $10,001 and $40,000, falls into the next bracket, taxed at 12%. You keep going like this, with each successive chunk of your income being taxed at progressively higher rates until you reach your top marginal tax rate.
This is where the real confusion often sets in: people think earning, say, $70,000 means you’re suddenly paying 24% on all of that. No! You’re only paying that higher rate on the portion of your income that falls into that 24% bracket. For 2023, if you were single, that bracket started around $89,000 of taxable income. So, someone earning $70,000 would likely have most of their income taxed at 12% and 22%, but not 24% at all. The US tax system is layered, like a cake, with each layer having its own price tag.
Honestly, the complexity of it all still gets under my skin sometimes. Trying to figure out your exact tax liability without making a mistake feels like solving a Rubik’s Cube blindfolded. You have to consider your taxable income, which isn’t your gross income; it’s after deductions and credits. This is a crucial distinction. For example, if your gross income was $75,000 but you had $15,000 in deductions, your taxable income would be $60,000. This means you’d be taxed based on the brackets applied to $60,000, not the full $75,000. You can find the official IRS tax brackets on their website, which is super helpful but still requires careful reading.
And it’s not just about the income itself; filing status matters big time. Whether you file as single, married filing jointly, married filing separately, or head of household completely changes the income ranges for each tax bracket. A married couple filing jointly often has much higher income thresholds for each bracket than a single person. This is designed to reflect the idea that two people might have more expenses, or simply more income to manage collectively. It’s a significant factor in your overall tax burden.
The biggest downside, in my opinion, is that this system can feel like a penalty for earning more. While the idea is that those with higher incomes can afford to pay a larger percentage, it can also discourage people from seeking higher-paying jobs or even starting businesses. If you know that an extra $10,000 could push you into a bracket where a significant chunk of that increase is immediately owed back to the government, it’s a tough pill to swallow. It’s this progressive taxation that drives the whole engine.
Look at it this way: for the 2023 tax year, the 12% bracket for single filers topped out around $44,725. If you earn $44,000, you’re comfortably in that bracket. But if you earn $45,000, that extra $1,000 pushes you into the 22% bracket. You won’t pay 22% on your whole $45,000, but that $1,000 difference will be taxed at 22%, adding roughly $120 more in taxes for that specific thousand dollars compared to earning $44,000. It’s marginal, but it adds up. You can see how this plays out across all the different rates on sites like Investopedia’s explanation of marginal tax rates.
But here’s the kicker: these brackets are for your taxable income, not your gross income. And taxable income is what’s left after you subtract deductions and credits. This is where things get really interesting and potentially save you a ton of money. Things like 401(k) contributions, IRA contributions, student loan interest deductions, and various tax credits can significantly lower your taxable income. A $2,000 tax credit, for example, directly reduces your tax bill by $2,000, which is far more impactful than a deduction that just lowers your taxable income.
The whole system is a balancing act designed by lawmakers. They adjust these bracket ranges and rates every year, often tied to inflation, to try and ensure fairness and fund government operations. The Tax Cuts and Jobs Act of 2017, for instance, significantly altered these brackets for several years. Understanding these changes and how they apply to your specific financial situation is key. You can usually find summaries of current tax law changes on reputable sites like the IRS.gov website or through financial news outlets like Forbes.
So, while the idea of tax brackets can seem intimidating, it’s really just a tiered system. The highest rate you’re subject to only applies to the portion of your income within that specific tier. It’s not a flat tax, and it’s definitely not as simple as just looking at a single percentage. And honestly, if you’re not paying attention to tax planning throughout the year, you’re probably leaving money on the table, which is a bigger sin than any tax bracket.